How to Document Tree Damage for Insurance

A fallen tree can turn a quiet morning into an urgent property problem. Before anyone starts cutting branches, moving debris, or covering roof damage, knowing how to document tree damage for insurance can protect your claim and help your adjuster see what happened.
Your first job is safety. Your second is preserving the evidence. Trees under tension, hanging limbs, downed power lines, and damaged roofs are not DIY cleanup situations. Take photos and notes from a safe location, then bring in qualified help when the tree or debris creates a hazard.
Start With Safety, Not Cleanup
Do not walk under broken limbs or climb onto a damaged roof for better photos. A tree that looks settled can shift without warning, especially after heavy rain, wind, or snow. Keep children, pets, tenants, and employees away from the area.
If a limb or trunk is touching a power line, stay clear and call your utility provider or emergency services. Do not attempt to move branches away from the line. If the tree has damaged your home, blocked an entrance, or is leaning over a building, take clear photos from the ground and arrange emergency tree service as soon as possible.
Insurance carriers generally expect you to take reasonable steps to prevent additional damage. That may mean placing a tarp over a roof opening, blocking off an unsafe area, or having a dangerous tree removed. It does not mean putting yourself at risk to save a few branches.
How to Document Tree Damage for Insurance
The strongest claim file tells a simple, complete story: what your property looked like, what the storm did, what was damaged, and what you did to stop the problem from getting worse. Start documenting before cleanup begins whenever it is safe to do so.
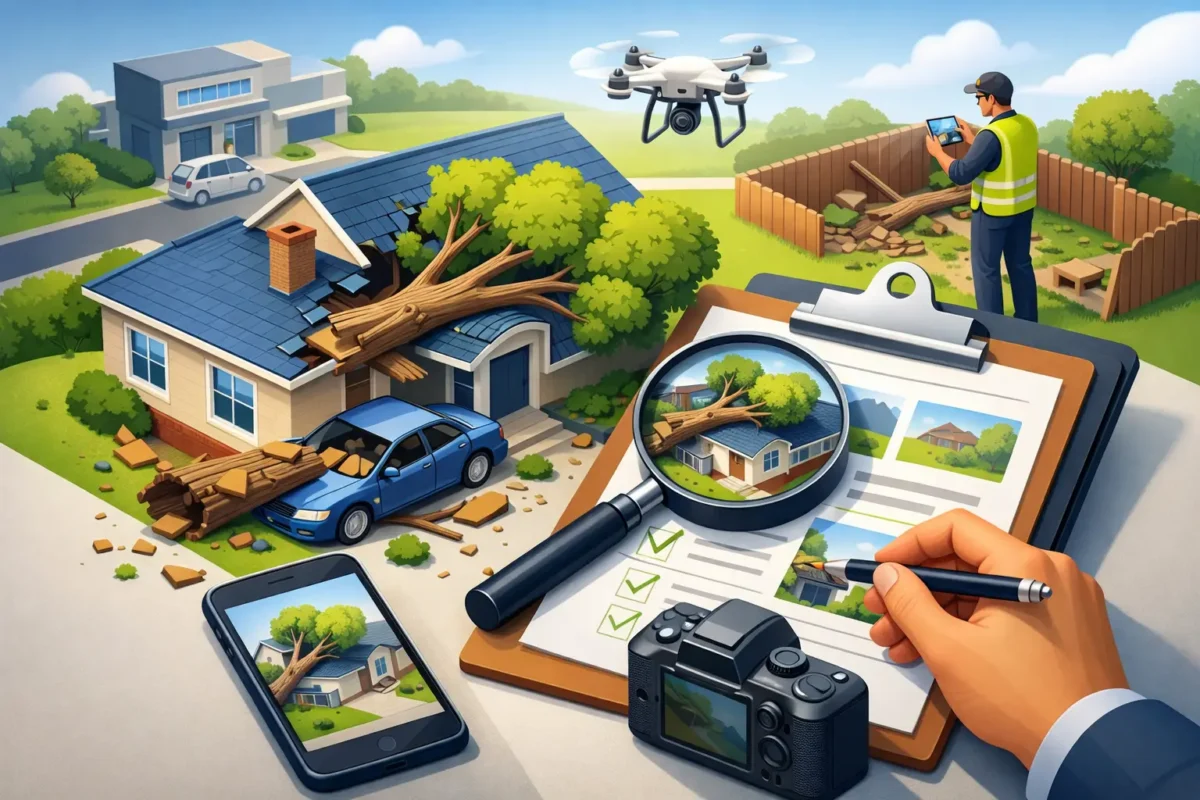
Take wide photos first. Stand far enough back to show the entire tree, its location, and its relationship to your house, garage, fence, driveway, vehicle, or neighboring property. Then take medium-distance shots and close-ups of specific damage, such as crushed gutters, broken shingles, cracked siding, shattered windows, or uprooted soil.
Use video too. Walk slowly around the area from a safe distance and narrate what you see. Mention the date, approximate time of the storm, your address, and the damaged areas. Video can be especially useful when a large limb is resting on a roof or a tree has blocked access to part of the property.
Make sure your photos show these details:
- The full tree or fallen limb before it is cut, hauled away, or moved
- Damage to structures, vehicles, fences, landscaping, and personal property
- The point where the tree broke, split, uprooted, or struck the building
- Weather-related evidence, such as snow load, storm debris, wind damage, or saturated ground
- Any temporary protection you install, including tarps, boards, or barriers
If possible, turn on date and location settings in your phone camera. Do not rely on those settings alone, though. Keep your own written record as well.
Write Down What Happened While It Is Fresh
A few clear notes can prevent confusion later. Record the date and time you discovered the damage, what weather occurred, and which areas of your property were affected. Note whether the tree was on your property, a neighbor’s property, or near a shared boundary.
Include what you observed before the storm if you know it. For example, you may remember that the tree looked healthy, or you may have noticed dead limbs, a visible crack, a lean, or decay near the base. Be accurate. Do not guess about the cause if you are not sure.
Also keep a record of every call, email, claim number, inspection appointment, and conversation related to the loss. Write down the representative’s name, the date, and what they told you. This is particularly helpful if storm claims are widespread and your insurer has a high volume of cases.
Save Every Estimate, Invoice, and Receipt
Once the area is documented, get a written assessment from a qualified tree service company. The estimate should identify the work needed, such as emergency tree removal, hazardous limb removal, storm debris cleanup, roof access assistance, or stump work. It should also separate urgent safety work from optional work whenever possible.
Keep the estimate, final invoice, payment receipt, and proof of any temporary repairs. If you buy tarps, plywood, buckets, or other supplies to limit additional water damage, save those receipts too. These costs may matter when your claim is reviewed.
Do not assume every tree-related expense is covered. Many homeowners policies cover sudden damage from a fallen tree when it hits a covered structure, but coverage for removing a tree that lands in an open yard can be limited or excluded. Policies may also have separate limits for debris removal, landscaping, fences, or tree removal.
Coverage can also depend on why the tree fell. A healthy tree that comes down in a windstorm is different from a tree that was clearly dead, neglected, or previously identified as hazardous. Your insurer will make the coverage decision, but clear documentation gives them better information to work with.
Do Not Throw Away the Evidence Too Soon
You may need to remove a tree quickly to protect your home or restore access. That is often the right call. Still, do not let all the evidence disappear before your insurer has a chance to review it.
Ask your tree contractor to take before-and-after photos of the work. Request photos of the broken trunk, root ball, decay, split leader, or damaged limbs if those details help explain the failure. Save a small section of damaged wood only if your insurance carrier requests it and it can be kept safely out of the way.
In many cases, the tree itself does not need to stay on your property. Photos, video, an itemized invoice, and a professional assessment are usually far more practical than leaving a dangerous trunk across your driveway for days.
Contact Your Insurance Company Promptly
Report the loss as soon as you have the basics documented. Give the insurer a straightforward description of what happened and tell them about any immediate safety work you needed to authorize. Ask whether they want to inspect the damage before permanent repairs begin.
You should also ask about your deductible, debris removal limits, and whether the adjuster needs additional photos or contractor documentation. If a tree from a neighboring property caused damage, notify your insurer anyway. Do not delay your claim while trying to decide who is responsible.
Avoid signing broad repair agreements or approving non-emergency work before you understand the scope of the damage and your insurance process. Emergency removal may be necessary, but replacement roofing, structural repairs, and major restoration work often need more coordination.
Common Documentation Mistakes That Can Slow a Claim
The most common mistake is cleaning up first and taking pictures later. Once the tree is cut into pieces and the roof is tarped, it can be difficult to show the original situation.
Another problem is submitting only close-up photos. Close-ups show damage, but they may not show how the tree caused it. Use a mix of wide, medium, and detailed images. It also helps to avoid blurry nighttime photos when possible. If you must document damage in the dark, take another set in daylight.
Finally, do not exaggerate damage or include old damage as part of a new storm claim. Insurers can usually identify inconsistencies, and an accurate claim is easier to process. If you are uncertain whether damage is new, take photos and let the adjuster review it.
When You Need Emergency Tree Help
Call for professional help right away if a tree has landed on a structure, is hanging over a roof, has uprooted near your foundation, blocks your driveway, or creates a risk to people nearby. In Albany County and across storm-prone parts of New York, heavy snow, saturated soil, and high winds can turn a weakened tree into an emergency quickly.
AAA Tree Service NY can help document the condition of the tree, remove immediate hazards safely, and provide clear written estimates for the work performed. The priority is to make your property safe without doing unnecessary work.
Take the photos, save the paperwork, and act quickly when the tree is unsafe. The goal is not to create a perfect insurance file while a hazard sits over your home. It is to protect your family and property while leaving a clear record of what the storm changed.